Gross Is a Headline. Net Is a Bank Balance.
Every year, professional contracts, endorsement deals and NIL checks generate massive headlines. Sports media reports the gross contract value, the $10 million season, the $250,000 NIL agreement or the record-breaking signing bonus.
Those numbers are only the beginning of the financial story.
Between federal taxes, state income taxes, out-of-state jock tax obligations, agent and representation fees, business expenses and the cost of maintaining an athletic career, the amount attached to the headline can look very different from the capital an athlete actually keeps.
Apostle Sports Media (APSM) exists to explain that difference.
APSM covers the Net Reality of sports finance: how market value becomes gross income, how gross income becomes net income, and how retained capital can eventually become assets and wealth.
What Net Reality Means
Sports money moves through layers.
An athlete can have a multimillion-dollar market valuation without earning that exact amount. An athlete can earn millions in gross income without keeping millions after taxes and fees. And even a large net income figure does not automatically become long-term wealth.
APSM separates those stages instead of treating them as one number.
Market Value → Gross Income → Taxes & Costs → Net Income → Retained Capital → Assets & Wealth
That framework powers APSM’s roster valuations, contract analysis, tax research, athlete wealth coverage and the APSM Net Income Calculator.
The goal is not to promise athletes a financial outcome or tell readers what they should buy.
The goal is to make the financial mechanics visible.
What APSM Covers
The topics across APSM are different, but they ultimately return to the same question:
What does the headline number actually become?
Contracts & Realized Income
APSM breaks down headline contracts and athlete compensation into the financial pieces underneath them: guaranteed money, signing bonuses, annual cash flow, tax exposure, representation costs and estimated net take-home income.
A $100 million contract is an important number. It is not the same thing as $100 million of retained wealth.
State Taxes, Jock Tax & Residency
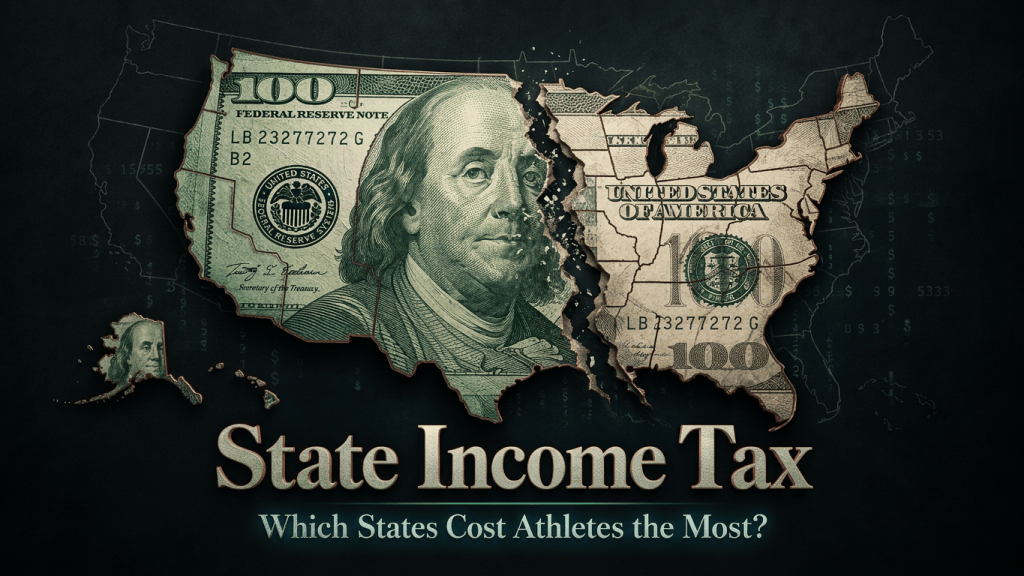
Where an athlete earns income can materially change what remains afterward. APSM tracks state income-tax systems, out-of-state duty-day taxation, sales and property taxes, cost of living and residency rules across the United States, Washington D.C. and Puerto Rico.
The purpose is to show why identical gross earnings can produce different financial outcomes in different jurisdictions.
Real Estate & Asset Ownership
Athlete real estate is more than mansion photography.
APSM follows purchases, sales, appreciation, property taxes and location to understand how real estate fits into the larger financial lives of athletes, coaches and sports executives.
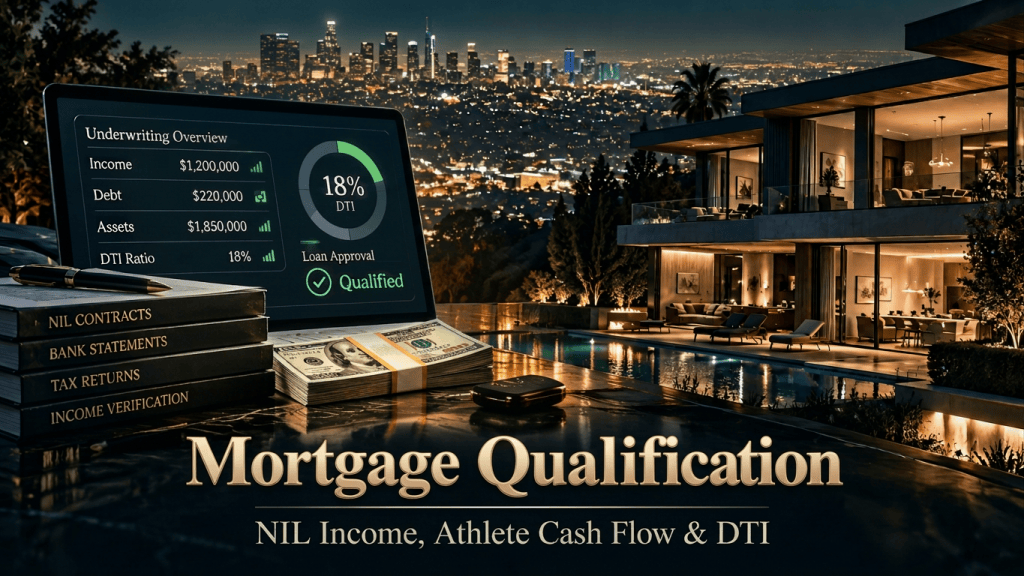
The property itself is only one part of the story. Financing, taxes, equity and opportunity cost determine the larger Net Reality.
Team & League Finances
Athlete compensation exists inside much larger businesses.
APSM covers franchise and roster valuations, stadium financing, salary-cap mechanics, media rights, institutional revenue sharing and league revenue to explain where sports money originates before it reaches an athlete.
Sports Business, Regulation & Financial Risk
Sports finance also includes the companies, laws and financial structures surrounding competition.
APSM covers sponsorships, betting markets, investigations, fraud, regulatory compliance and other business decisions that can create, transfer or destroy value across the sports economy.
The APSM Standard: Institutional Depth, Public Clarity
APSM is built around a simple editorial standard: the research should be detailed enough to be useful to an agent, CPA, financial professional or industry operator while remaining understandable to an athlete, student or fan who simply wants to learn how the money works.
APSM is not designed to chase every trade rumor, coaching rumor or breaking-news cycle. When current events matter, they are used to explain the financial story underneath them.
Research can include tax statutes, court filings, public financial records, university and league disclosures, contract reporting, corporate announcements, industry data and other publicly available sources.
APSM then connects those inputs through a consistent financial framework rather than presenting every large number as if it measures the same thing.
Gross value, market value, income, net income and wealth are different financial concepts. APSM treats them that way.
Who Builds APSM
Apostle Sports Media was founded by Aidan Anderson as an independent sports-finance media and education platform.
APSM remains independently researched and operated and focuses on being built around a larger objective: create a public financial layer for sports where athletes, families, fans and industry professionals can follow the money from the headline number to its actual financial outcome.
being built around a larger objective: create a public financial layer for sports where athletes, families, fans and industry professionals can follow the money from the headline number to its actual financial outcome.
Advertising, sponsorships and commercial partnerships support the business, but they do not determine APSM’s editorial conclusions or financial models.
Start With the Net Reality
For readers who want to see the framework in action, the best starting points are APSM’s free tools and reference libraries.
Use the APSM Net Income Calculator to model what gross athlete income can become after federal taxes, state taxes, representation fees and career expenses.
Or explore the State Athlete Tax Glossary for jurisdiction-by-jurisdiction coverage of income taxes, jock taxes, residency, housing costs and the tax environment surrounding athlete earnings.
The headline tells you what the money looks like.
APSM explains what happens next: Net Reality.
Business Inquiries & Direct Media Placements
For sponsorships, direct media placements, commercial partnerships and other business opportunities: