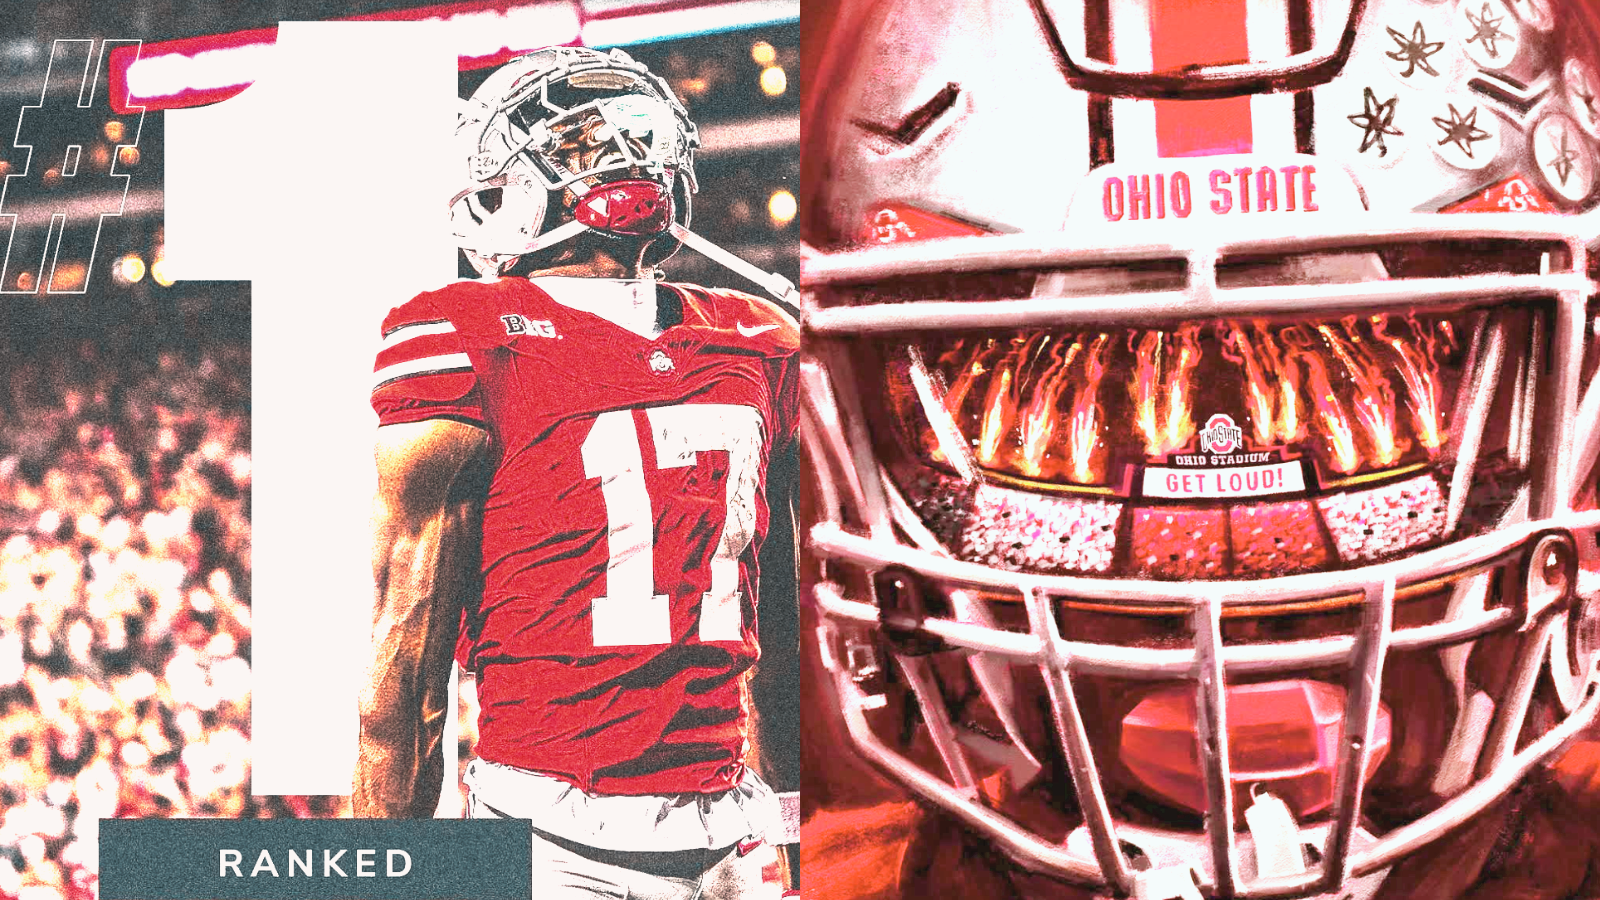
Ohio State’s 2026 roster provides one of the clearest examples of what college-football spending looks like when most of the value was developed before it had to be replaced.
And after October 17th, the Buckeyes have a timely result to match.
No. 4 Ohio State went into Bloomington and beat No. 5 Indiana 19-15, ending the defending national champion Hoosiers’ 22-game winning streak and handing Indiana its first home loss in nearly three years.
The game quite literally came down to centimeters: with just over a minute remaining, Indiana receiver Nick Marsh broke open on fourth down for what would have been the go-ahead touchdown, but his left foot landed out of bounds in the end zone.
The result matters here for a simple reason. Texas, which still owns APSM’s No. 1 roster valuation, has now lost two straight games, while Ohio State just knocked off one of the best teams in the country.
The Buckeyes did lose to Texas earlier this season, so one Saturday does not rewrite the entire hierarchy. It reinforces the distinction at the center of Ohio State football’s Net Reality:
roster value can buy access to elite talent, but it cannot guarantee execution.
Ohio State may not yet own the No. 1 spot in the AP Poll or APSM’s financial model, but it is moving closer to the top of both conversations.
APSM currently places the Buckeyes inside an estimated $37 million – $39 million open-market player-value range, with the current player-level dataset centered around a ~$38 million working midpoint across 80 priced players.
That ranks Ohio State No. 4 nationally and No. 2 in the Big Ten in APSM’s current model. Approximately 65% of the midpoint is attached to retained players, while portal additions represent roughly 21% and incoming recruits account for another 14%.
Under APSM’s separate standardized $1 million tax-only benchmark, Ohio produces a Net Retention Score of 61/100.
Those numbers explain the financial structure better than calling the Buckeyes a $38 million “payroll.” Most of Ohio State’s modeled player value belongs to athletes the program already recruited and developed.
The transfer portal still matters, but the larger financial job is protecting an existing portfolio from becoming somebody else’s portal class.
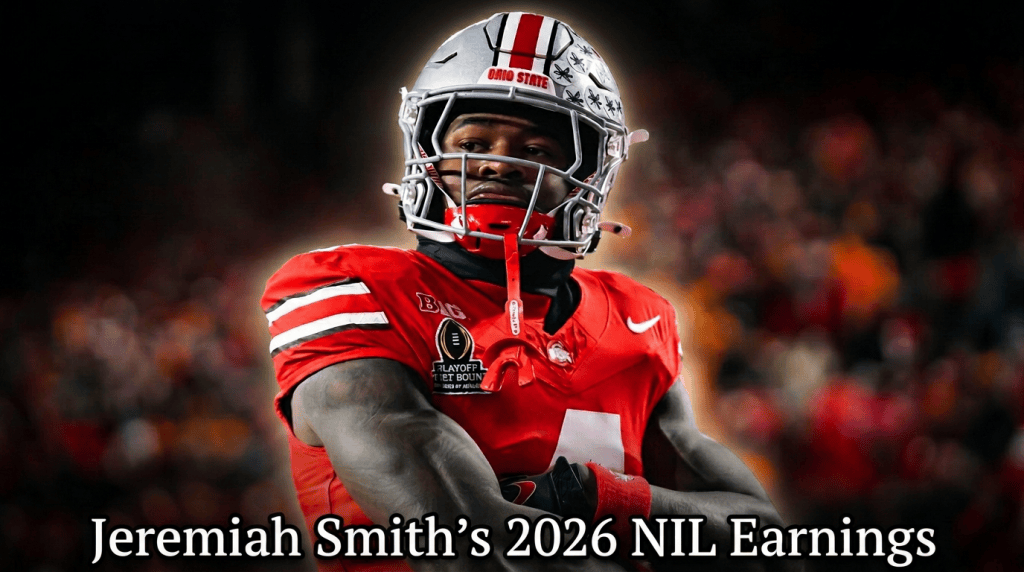
At the top of that portfolio sits Jeremiah Smith.
APSM currently values Smith around $5 million, giving Ohio State one of college football’s most valuable individual commercial assets at wide receiver while still carrying seven-figure value at quarterback, offensive tackle and edge.
Smith also delivered the biggest offensive play of Saturday’s win, catching a 38-yard fourth-down touchdown that gave Ohio State a 19-7 fourth-quarter lead and tied the Big Ten career record for touchdown receptions.
Ohio State’s roster value does not guarantee wins. But when the Buckeyes needed a play against a top-five opponent, one of the most valuable athletes in APSM’s model delivered the play that ultimately separated the teams.
The roster estimate measures the open-market value attached to those players. It does not represent every dollar Ohio State spends on football, nor is it a disclosed list of athlete salaries.
Direct university revenue sharing exists beside third-party NIL, sponsorships, licensing, appearances and other commercial income. Coaching salaries, recruiting, facilities, travel, medical support and staff sit elsewhere in the operation.
Those financial layers interact. They are not the same number.
For the athlete, even market value is only the starting point. Gross compensation still has to survive federal taxes, Ohio state income tax, applicable employment or self-employment taxes, representation costs and personal financial decisions before it becomes usable capital.
The first APSM projection below begins with the current ~$38 million midpoint inside Ohio State’s $37 million–$39 million 2026 roster range and applies the same illustrative 7% annual market-growth assumption used throughout the CFB roster series.
It is not a prediction of an exact future payroll.
It illustrates what continued market expansion, direct athlete compensation and Ohio State’s ability to retain premium talent could mean for the value of the roster over the next decade.

How Ohio State Built Its 2026 CFB Roster Around Retention
Ohio State’s current roster is not as simple as Jeremiah Smith plus the rest of the other football players.
It is a player portfolio assembled through three different acquisition markets: retention, the transfer portal and high-school recruiting.
- Retained players: ~$24.6 million | 65%
- Portal additions: ~$8.1 million | 21%
- 2026 recruits: ~$5.3 million | 14%
The split shows where Ohio State’s financial strength really sits. Nearly two-thirds of the roster’s estimated market value is attached to players the Buckeyes already recruited and developed, while the portal and incoming class account for the remaining 35%.
That matters because the transfer portal has turned retention into an annual financial decision. The Buckeyes’ current roster valuation reflects two related forms of value:
what its players could command in the open market if they left, and the economic value of keeping those players in Columbus rather than allowing another program to acquire them.
Ohio State’s Top 5 2026 CFB Player Valuations
| Player | Pos. | Est. 2026 NIL Value | Share of Midpoint |
|---|---|---|---|
| Jeremiah Smith | WR | $5,000,000 | 13.2% |
| Julian Sayin | QB | $2,500,000 | 6.6% |
| Kenyatta Jackson Jr. | EDGE | $1,600,000 | 4.2% |
| Phillip Daniels | OT | $1,250,000 | 3.3% |
| Beau Atkinson | EDGE | $1,150,000 | 3.0% |
These five players represent approximately $11.50 million, or about 30% of the entire roster valuation. The remaining roughly $26.5 million is distributed among the other 75 players.
The current roster also includes “honorable mentions” of Ian Moore at approximately $1.1 million, Luke Montgomery at $1 million, and Devin McCuin also at $1 million, as well as several additional players valued at approximately $900,000 or more. (these are gross figures)
This distribution illustrates that Ohio State’s financial model is not concentrated entirely at quarterback and wide receiver. Significant estimated value exists on both sides of the ball and across the offensive and defensive line.
Jeremiah Smith | $5.0 Million | Wide Receiver
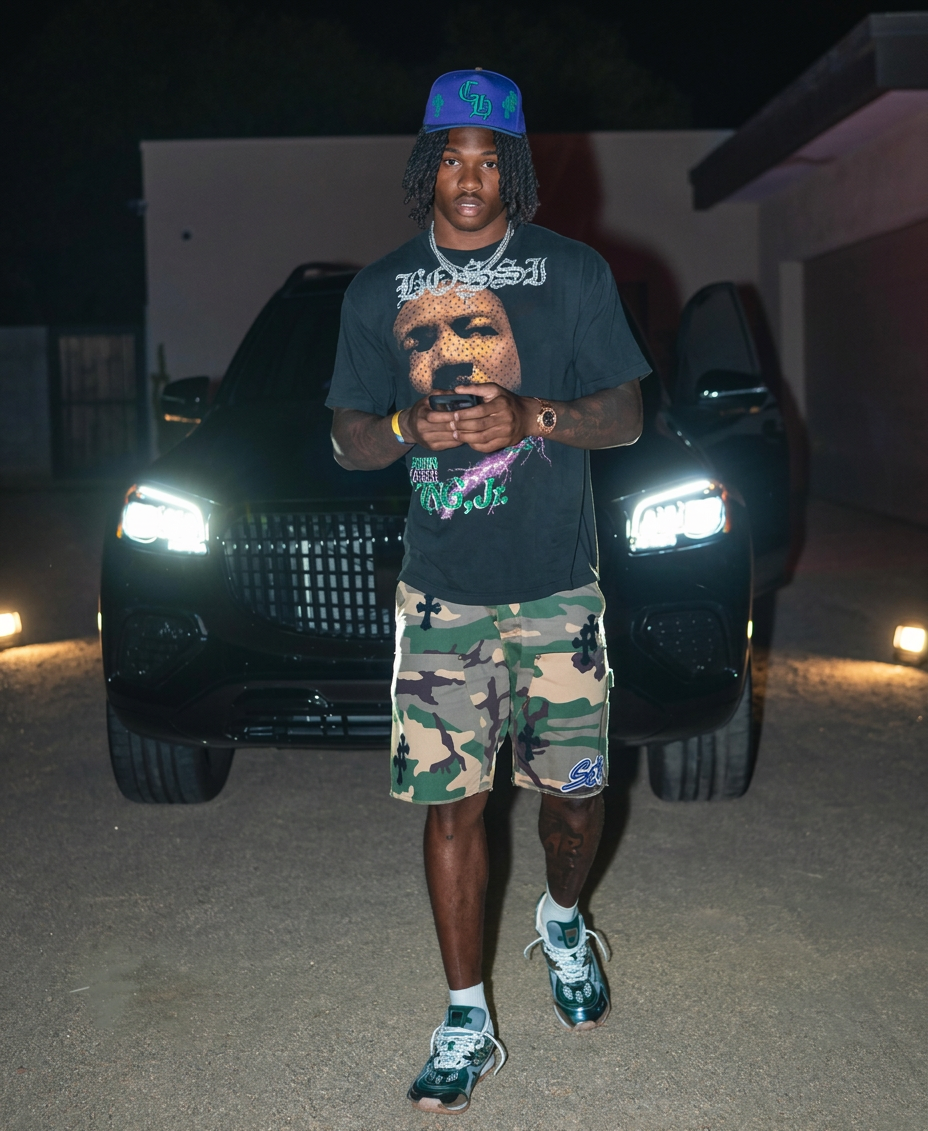
Jeremiah Smith is the undisputed anchor of Ohio State’s financial ecosystem. With an estimated $5 million open-market valuation, Smith’s economic footprint extends far beyond localized revenue-sharing or collective payouts.
He has built a commercial brand that rivals professional athletes, securing national NIL partnerships with Red Bull, Lululemon, American Eagle, Adidas, Nintendo, and Ricart Automotive.
While the exact cash value of these individual agreements remains private, they prove a crucial point: elite college athletes possess massive commercial equity independent of their universities.
Smith’s partnership with KeyBank is particularly instructive. Rather than a standard social media ad, the bank leveraged Smith’s platform for a financial literacy campaign, showing that top-tier NIL valuations are evolving from traditional marketing into sophisticated partnerships.
Julian Sayin | $2.5 Million | Quarterback
Valued at nearly $2.5 million, Sayin holds the second-highest spot on the roster, reflecting the undeniable reality of quarterback economics.
In the modern college market, proven QBs command an automatic premium because their performance dictates the productivity, and therefore the financial value, of the entire offense.
Sayin’s profile also highlights a critical distinction in sports business data: a published NIL valuation is an estimated open-market price, not a guaranteed salary.
His $2.5 million figure represents what the market dictates his combination of talent, scarcity, and brand reach is worth, rather than a publicly verified 1099 form from a university.
Kenyatta Jackson Jr. | $1.6 Million | EDGE
As the highest-valued defender on the roster, Kenyatta Jackson Jr. illustrates how capital is allocated on the defensive side of the ball.
The modern college football economy attaches massive premiums to scarcity, as the rare athletic ability required to pressure opposing quarterbacks is one of the most sought out talents in the sport both in college and in the NFL.
Jackson’s $1.6 million valuation proves that Ohio State’s multi-million-dollar roster-value structure is not just a collection of offensive skill players; it requires heavy investment in premium defensive disruptors.

Phillip Daniels | $1.25 Million | Offensive Tackle
In college football capital allocation, an offensive tackle is essentially an insurance policy for your most expensive assets. Phillip Daniels carries an estimated value of $1.25 million, demonstrating the direct financial relationship between roster construction and player protection.
You do not invest $7.5 million in a quarterback and wide receiver without buying the elite talent required to protect them.
The market clearly recognizes this unit’s value.
Fellow linemen Moore and Montgomery also carry estimated valuations north of $1 million, proving that keeping the offense upright requires a massive, multi-player financial commitment.
Beau Atkinson | $1.15 Million | EDGE
Rounding out the top five is Beau Atkinson, with an estimated 2026 market value sitting at $1.15 million.
When paired with Jackson Jr., Atkinson’s valuation reveals that Ohio State has consolidated immense financial capital into its defensive front.
The presence of multiple seven-figure edge rushers and defensive linemen confirms that a $38 million roster valuation isn’t artificially inflated by three superstars; it requires deep, systemic investment across the entire line of scrimmage.
Ohio State’s Roster Valuation Is Separate From Revenue Sharing
Ohio State entered the House-settlement era expecting to fully fund approximately $20.5 million in direct student-athlete compensation during 2025-26 while continuing to operate all 36 varsity sports.
That was the first-year number.
For the 2026–27 academic year, the settlement-wide institutional cap increased to approximately $21.58 million per participating school.
Neither figure should be interpreted as Ohio State football’s payroll.
- $37 million–$39 million is APSM’s current estimate of Ohio State football’s open-market player-value range.
- ~$38 million is APSM’s current working midpoint.
- ~$21.58 million is the current schoolwide institutional compensation ceiling across participating sports.
Actual player earnings depend on the agreements attached to each athlete, while legitimate third-party NIL can exist separately from institutional revenue sharing.
The numbers are related, but not interchangeable. Ohio State has not publicly disclosed a precise football-only revenue-sharing figure.
Third-Party NIL Adds Another Revenue Layer
The House v. NCAA settlement didn’t bottle up player compensation. It institutionalized it. While schools can now share revenue directly with athletes, the private market is still thriving.
The House-settlement structure still permits legitimate third-party NIL agreements when they satisfy the applicable business-purpose and compensation rules, while the IRS governs how those earnings are taxed.
According to data released by the College Sports Commission (CSC), the regulatory body cleared more than $227 million in NIL deals over a single two-month summer window, processing thousands of contracts.
Of that total, roughly $188.6 million involved “associated entities” (boosters or collectives tied to schools) requiring strict compliance reviews, while the rest came from traditional, independent corporate sponsors.
This matters directly for Ohio State. A ~$38 million working midpoint isn’t just a reflection of institutional checks; it’s a snapshot of a hybrid economy where multiple income streams collide:
- Institutional Revenue Sharing: Direct checks from the university athletic department.
- Third-Party Collectives: Booster-backed or associated entity support cleared through the CSC.
- Independent Commercial Deals: A star receiver signing a national apparel contract, a quarterback anchoring an ad campaign, a volleyball player monetizing social media, or a baseball player cashing in on custom merchandise.
The revenue source changes, but the underlying financial reality remains identical: a top-tier athlete’s earning power extends far beyond what any university payroll can write.
Corporate Sponsorship Also Contributes to the Athlete Economy
Ohio State’s commercial relationships provide another example of how institutional and individual athlete economics increasingly overlap. In July 2026, Ohio State announced a partnership with JPMorgan Chase covering all 36 varsity sports, including a jersey-patch relationship and resources supporting student-athletes and NIL opportunities.
ESPN reported the deal at approximately $17 million annually, although the university did not publicly disclose the full financial terms. The significance is not simply the size of one sponsorship, it’s that a large athletic brand creates an audience that pays.
That audience has commercial value to corporations, and some of that value can eventually reach individual athletes through sponsorships and other NIL opportunities. The university brand, team brand and individual athlete brand increasingly operate within the same commercial ecosystem.
Ryan Day’s $12.5 Million Contract Is Separate From Player Value
Ohio State head coach Ryan Day has a seven-year contract running through the 2031 season with $12.5 million in annual compensation, including a $2 million base salary. The agreement was announced after Ohio State’s 2025 national championship.
Contract reporting also identified an $11.5 million school buyout for each remaining year, a $6 million coach buyout, up to $1.55 million in annual incentives and a $250,000 retention bonus in 2027.
Day’s compensation is not included in the $38 million NIL roster valuation. His contract is compensation for the head coach; the $38 million is an estimate of player market value.
The comparison is still useful because it illustrates the scale of the organization. Ohio State is simultaneously operating a football roster with approximately $38 million of estimated player market value and a head-coach compensation package worth $12.5 million annually.
The athletic department also operates 36 varsity programs and a significant corporate partnership business. College athletics increasingly requires financial analysis that accounts for all of these layers rather than treating NIL as a single payment from a school to an athlete.
Using the same standardized framework APSM applies across the roster series, Day’s compensation also provides a useful gross-to-net example.
If his full $12.5 million annual compensation were modeled as W-2 income for a single filer, APSM estimates approximately $7.28 million could remain after 2026 federal income tax, employee Social Security and Medicare taxes and Ohio state income tax, before incentives, deductions, benefits, retirement contributions or individualized planning.
That represents roughly 58% of gross compensation under the standardized illustration. The example does not include a personalized municipal-tax calculation. Columbus imposes a 2.5% municipal income tax on qualifying wages and certain other compensation, which can create additional location-specific drag depending on where income is earned and where the taxpayer resides.
A $12.5 million coaching contract and a $12.5 million bank balance are two different numbers.
APSM estimate only: Day’s actual filing status, deductions, residence, benefits, contract structure and tax return are private. The example illustrates high-income contract mechanics rather than estimating his private tax liability.
Gross NIL Value Is Not Net Income
For an athlete, four different financial concepts should be kept separate:
- Market valuation: estimate of what athlete may be worth in the market.
- Gross income: compensation actually received.
- Net income: what remains after applicable taxes and expenses.
- Wealth: accumulated productive assets after spending and liabilities.
The IRS states that NIL income is generally taxable, including non-cash compensation such as merchandise, gift cards and services.
Depending on the structure of the relationship, an athlete may receive a W-2 or 1099-NEC, and income from personal services can be subject to federal tax, state-income taxes, and also additional employment or self-employment taxes depending on filing status.
Athletes also need to track expenses associated with producing NIL income and the locations where services are performed because state tax obligations can arise in more than one jurisdiction.
That means financial planning should begin when an NIL agreement is signed, not when the tax return is prepared.
Ohio’s 2026 Tax Environment
Ohio’s individual income-tax system changed substantially for 2026.
Under current Ohio law, taxable nonbusiness income above $26,050 is generally calculated using $332 plus 2.75% of the amount above that threshold.
That gives Ohio State athletes a lower state-income-tax burden than several major college and professional markets, but 2.75% is not the entire Net Reality.
Federal income tax remains the largest component for a seven-figure earner. Employment or self-employment treatment matters. Representation costs matter. Multistate income can matter.
And the city of Columbus itself adds another layer:
Columbus Municipal Income Tax
Columbus currently imposes a 2.5% municipal income tax on qualifying wages and certain other compensation.
That local tax is separate from Ohio’s state income tax. APSM’s standardized state-to-state Net Retention Score intentionally isolates the state benchmark so every jurisdiction can be compared on the same basis; actual Ohio State athletes living or earning income in Columbus may face additional municipal obligations depending on their circumstances.
Using the APSM Net Income Calculator framework, a standardized $2 million gross NIL example with Ohio as the primary state jurisdiction, a 3% representation estimate and 0% personalized expenses models approximately $1.12 million of retained capital, or about 56.1% of gross, before any individualized Columbus municipal-tax adjustment.
The same $2 million gross headline figure will not produce the same result for every athlete.
Cost of Living Advantage
Central Ohio’s cost of living tracks 7% to 9% below the national average. Combined with local housing markets that remain more accessible than major coastal metros, a dollar retained in Columbus simply buys more real estate, goods, and services.
Sales Tax Realities
While the state base sits at 5.75%, local county and transit additions bring the combined retail sales tax rate in Franklin County to 8.00%.
Property Tax Considerations
For athletes transitioning from dorms to purchasing luxury real estate or multi-family investments around the university, factoring in Ohio’s specific property tax rates is vital for long-term cash flow.
(Want to compare how Ohio’s tax structure stacks up against other sports hubs across the country? Dive into the complete breakdown over at the APSM State Tax Glossary for a full analysis of residency rules, multi-state athlete filing, and domicile compliance.)
Ultimately, an athlete’s net wealth isn’t just about what they earn on paper, it’s about how efficiently their home base lets them keep, spend, and compound it.

Ohio State Buckeyes Roster Net Reality
Because individual tax returns and representation agreements are private, APSM cannot determine an athlete’s exact take-home income from a market valuation alone.
The standardized player model uses 2026 progressive federal income tax, applicable self-employment/FICA treatment, Ohio’s state-income-tax structure, a 3% representation estimate and 0% invented personalized expenses.
That final assumption is intentional. Training, housing, travel, family support, legal work and other athlete-specific expenses vary too much to guess responsibly inside a roster article. Those belong inside the APSM Net Income Calculator, where the user can actually change them.
At the standardized $2 million Ohio benchmark, APSM models approximately $1.12 million of retained capital, or about 56.1% of gross before any individualized Columbus municipal-tax adjustment.
Because federal taxation is progressive, retention changes with gross income. The table below therefore calculates each rounded player value separately rather than applying one flat percentage to all five.
| Player | Gross Valuation | Illustrative Deductions | Illustrative Net Capital |
|---|---|---|---|
| Jeremiah Smith | $5,000,000 | ~$2,246,008 | ~$2,753,992 |
| Julian Sayin | $2,500,000 | ~$1,106,235 | ~$1,393,765 |
| Kenyatta Jackson Jr. | $1,600,000 | ~$695,916 | ~$904,084 |
| Phillip Daniels | $1,250,000 | ~$536,348 | ~$713,652 |
| Beau Atkinson | $1,150,000 | ~$490,757 | ~$659,243 |
Converting Ohio State NIL Income Into Long-Term, Generational Wealth
At the standardized $2 million Ohio example, APSM models approximately $1.12 million in retained capital before individualized municipal-tax exposure.
That does not mean APSM is recommending how an athlete should invest it. It shows the financial opportunity created when gross athlete income survives the first layer of taxes and fees.
An athlete still needs liquidity for housing, family obligations, training, legal and accounting expenses, transportation and ordinary life. But the difference between earning $2 million and retaining roughly $1.12 million is exactly why the Net Reality calculation comes first.
What One Season of Ohio State NIL Income Could Become if 20% of Net Take-Home Was Invested Over the Next Decade
For this illustration, 2026 is the only football-income year included in the model. No future Ohio State NIL income. No endorsement growth. No NFL salary. No additional investment contributions.
Each of the five players invests 20% of his modeled 2026 retained capital into historically proven wealth building vehicles once (index funds), and only that original investment compounds at an illustrative 8% annual return through 2036.
The starting amounts for the next graphic refresh are approximately $551K for Smith, $279K for Sayin, $181K for Jackson, $143K for Daniels and $132K for Atkinson.
At an illustrative 8% annual return through 2036, those original amounts grow to roughly $1.19M, $602K, $390K, $308K and $285K, respectively.
The point is not to predict anybody’s future net worth. It is to show what one college earning window can do before another NIL payment or professional contract is added.
For the standardized illustration below, APSM uses a one-time 20% investment only as a comparison tool, not a recommendation.

Why This Data Matters
The point of this projection is not that Ohio State’s five highest-valued players are guaranteed to produce these exact investment balances. Markets move, returns fluctuate, and each athlete will make different financial decisions. The point is how much one year of high-level NIL earning power can change an athlete’s financial starting line.
In this model, none of the five players earn another dollar from NIL, endorsements, or professional football after 2026. They simply invest 20% of their estimated net earnings once and allow that capital to compound for the next decade.
That matters because today’s elite college athlete can reach the NFL with assets already working for them before their first pro check ever clears their checking account. Consider two rookies who eventually sign identical NFL rookie contracts:
- Player A enters the league with $50,000 in liquid savings and no meaningful investment portfolio.
- Player B enters with hundreds of thousands of dollars already invested and years of compounding working in their favor.
Their rookie salaries may be identical, but their financial positions are not. Player B has more capital available for investments, real estate, business opportunities and long-term reserves, while also becoming less dependent on the next contract to create financial security.
That is one of the biggest changes NIL has created in college sports. The modern athlete is no longer only playing for a draft grade or future professional payday. For the athletes who manage it correctly, college itself can become the first stage of wealth creation.
APSM Net Retention Score: Ohio 61/100
Ohio State’s broader financial position becomes easier to compare once the player-specific Net Reality calculation is separated from APSM’s standardized Net Retention Score. The score begins every jurisdiction with the same $1 million of gross athlete income.
Agent fees and personalized expenses are removed so the benchmark isolates the underlying federal and state tax environment rather than an athlete’s private representation agreement or spending decisions.
Under that standardized model, Ohio produces an APSM Net Retention Score of 61/100.
That should not be confused with the approximately 56.1% retained at the $2 million Ohio State player benchmark. The $2 million player model includes a 3% representation estimate and uses a different gross-income level.
The Net Retention Score fixes gross income at $1 million and removes representation and personalized expenses so Ohio can be compared directly with Texas, Alabama, Mississippi, Georgia and every other jurisdiction.
Ohio’s 2.75% state-income-tax structure gives athletes a stronger tax-only starting position than several higher-tax markets.
Columbus municipal taxation can still create additional local drag, which is why the Retention Score should be viewed as the standardized state-level benchmark, not a prediction of every Buckeye’s tax return.
Financial Implications of Ohio State CFB Roster’s Net Reality for Athletes, Agents and Sponsors
The 2026 Ohio State roster isn’t just a football team; it is a fully operational financial enterprise. We have officially crossed the threshold from amateur athletics into a complex, multi-tiered economic system.
In the transfer portal era, keeping the talent you already developed is just as expensive as acquiring it. This ecosystem fundamentally changes the job description for everyone involved:
For Athletes
Ohio’s 61/100 APSM Net Retention Score gives Ohio State athletes a relatively strong state-level tax starting point.
But the score is only the baseline. Federal taxation, income structure, representation, municipal exposure and personal expenses still determine how much of an athlete’s gross earning power becomes usable capital.
A $5 million market valuation can create extraordinary economic opportunity. It does not automatically create a $5 million balance sheet.
For Agents
Roughly 65% of Ohio State’s current midpoint belongs to retained players.
That makes retention negotiations, portal leverage, third-party commercial opportunities and the athlete’s eventual net position increasingly important parts of representation.
The question is no longer just what another program offers upfront, what amenities it has or how impressive the facilities look. In this generation, it is also what each offer becomes after taxes, fees and location are considered.
For Sponsors
Ohio State gives sponsors access to athletes whose audiences can operate independently of the university itself.
Smith’s national partnerships show what happens when elite performance, Ohio State exposure and an athlete’s own brand overlap.
- The school creates reach.
- The athlete creates individual commercial value.
- The sponsor decides what that attention is worth.
For Ohio State
Ohio State’s financial challenge is capital allocation across one of the largest athletic portfolios in the country. The department has to fund institutional athlete compensation, retain elite football players, use the portal, recruit, operate 36 sports, pay a $12.5 million head coach and support the infrastructure surrounding the entire program.
Those costs interact. They do not belong inside one fictional payroll.
Bottom Line
Ohio State currently sits inside APSM’s estimated $37 million–$39 million 2026 football roster-value range, with the current player-level dataset centered around a ~$38 million working midpoint.
Approximately 65% of that value belongs to retained players, 21% to portal additions and 14% to recruits.
That is the financial identity of the Buckeyes’ roster.
Ohio State is spending in the portal, but the larger investment is tied to talent it already recruited, developed and now has to keep.
Jeremiah Smith sits at the top of that portfolio with roughly $5 million in modeled open-market value, while quarterback, offensive tackle and edge give the roster meaningful financial depth beyond one superstar.
Around the players sits a much larger enterprise: a $21.58 million 2026–27 schoolwide institutional compensation ceiling, independent NIL and sponsorship activity, a $12.5 million head coach and the infrastructure required to operate 36 varsity sports.
Those figures do not belong to one accounting bucket.
For the athlete, Ohio’s 61/100 APSM Net Retention Score provides the state-level starting point underneath the individual Net Reality calculation.
- Gross value is not income.
- Income is not net income.
- And net income is not wealth.
Whatever survives taxes, fees and spending still has to become productive capital before a short athletic earning window can create lasting financial security.
That is the Net Reality.
Ohio State 2026 CFB Roster FAQs
What is Ohio State football’s 2026 roster worth?
APSM currently places Ohio State’s 2026 football roster inside an estimated $37 million–$39 million open-market range, with a current working midpoint of approximately $38 million across 80 priced players. Approximately 65% of that midpoint is tied to retained athletes, with portal additions accounting for ~21% and recruits another 14%.
Who are Ohio State’s five highest-valued football players in 2026?
Ohio State’s five highest-valued players carry approximately $11.5 million in combined estimated market value, equal to roughly 30.3% of APSM’s current ~$38 million midpoint.
- Jeremiah Smith (WR): ~$5.0M
- Julian Sayin (QB): ~$2.5M
- Kenyatta Jackson Jr. (EDGE): ~$1.6M
- Phillip Daniels (OT): ~$1.25M
- Beau Atkinson (EDGE): ~$1.15M
Smith alone represents roughly 13% of the midpoint, but substantial value also sits at quarterback, offensive tackle and edge.
Is Ohio State actually paying its football players $37 million–$39 million?
No. The $37 million–$39 million range is APSM’s estimate of Ohio State football’s open-market player value, not a disclosed university payroll. Institutional revenue sharing, third-party NIL, sponsorship income, coaching compensation and the broader cost of operating Ohio State athletics are separate financial categories.
How much does a $2 million Ohio State NIL athlete keep under the APSM model?
Using APSM’s standardized 2026 framework with progressive federal taxation, applicable self-employment/FICA treatment, Ohio’s state-income-tax structure, a 3% representation estimate and 0% personalized expenses, the $2 million benchmark models approximately $1.12 million of retained capital, or roughly 56.1% of gross before individualized municipal-tax exposure.
Actual results can vary based on income structure, filing status, residency, local tax obligations and other individual circumstances.
What is Ohio’s income tax rate for athletes in 2026?
For taxable years beginning in 2026, Ohio generally applies $332 plus 2.75% of taxable nonbusiness income above $26,050. Columbus separately imposes a 2.5% municipal income tax on qualifying wages and certain other compensation.
Under APSM’s standardized $1 million tax-only state benchmark, Ohio produces a Net Retention Score of 61/100.
Next Reads
- Texas 2026 CFB Roster Valuation: Net Reality
- Georgia 2026 CFB Roster Valuation: Net Reality
- Alabama 2026 CFB Roster Valuation: Net Reality
- Ole Miss 2026 CFB Roster Valuation: Net Reality
- Ohio Athlete Taxes
Disclaimer: This article contains general financial information for educational purposes and does not constitute professional advice. APSM estimates are derived from publicly available information, tax assumptions, finance modeling, and industry-standard fee structures. Actual earnings may vary based on residency elections, private contract provisions, image/media rights agreements, bonuses, and tax filings.