
If you want to understand how an SEC powerhouse constructs a contender in the modern college-football economy, follow the money to Athens. Georgia is one of the clearest examples of what elite roster construction looks like when the transfer portal is only part of the financial equation.
APSM currently places the Bulldogs’ 2026 football roster inside an estimated $29 million – $31 million open-market player-value range, with a current working midpoint of ~$30.1 million across roughly 100 valued players.
Approximately 74% of that midpoint is tied to retained players, while portal additions represent roughly 12% and incoming recruits account for 14%.
Under APSM’s separate standardized $1 million tax-only benchmark, Georgia produces a Net Retention Score of 59/100.
That combination tells the real Georgia story. Kirby Smart’s program is not primarily rebuilding through annual portal spending. Most of the underlying market value remains attached to athletes Georgia recruited, developed and then had to retain in an environment where another school can attempt to turn a developed player into its own asset.
The broader UGA football operation is much larger than the roster itself.
Direct institutional revenue sharing, independent NIL, sponsorships, coaching salaries, recruiting infrastructure and operating expenses all sit around the player market, but they are separate financial categories.
APSM’s roster valuation measures the estimated economic value of the athletes themselves. And even that value is only the beginning of the athlete’s personal financial equation.
A market valuation is not guaranteed compensation, gross compensation is not net income, and net income does not automatically become wealth.
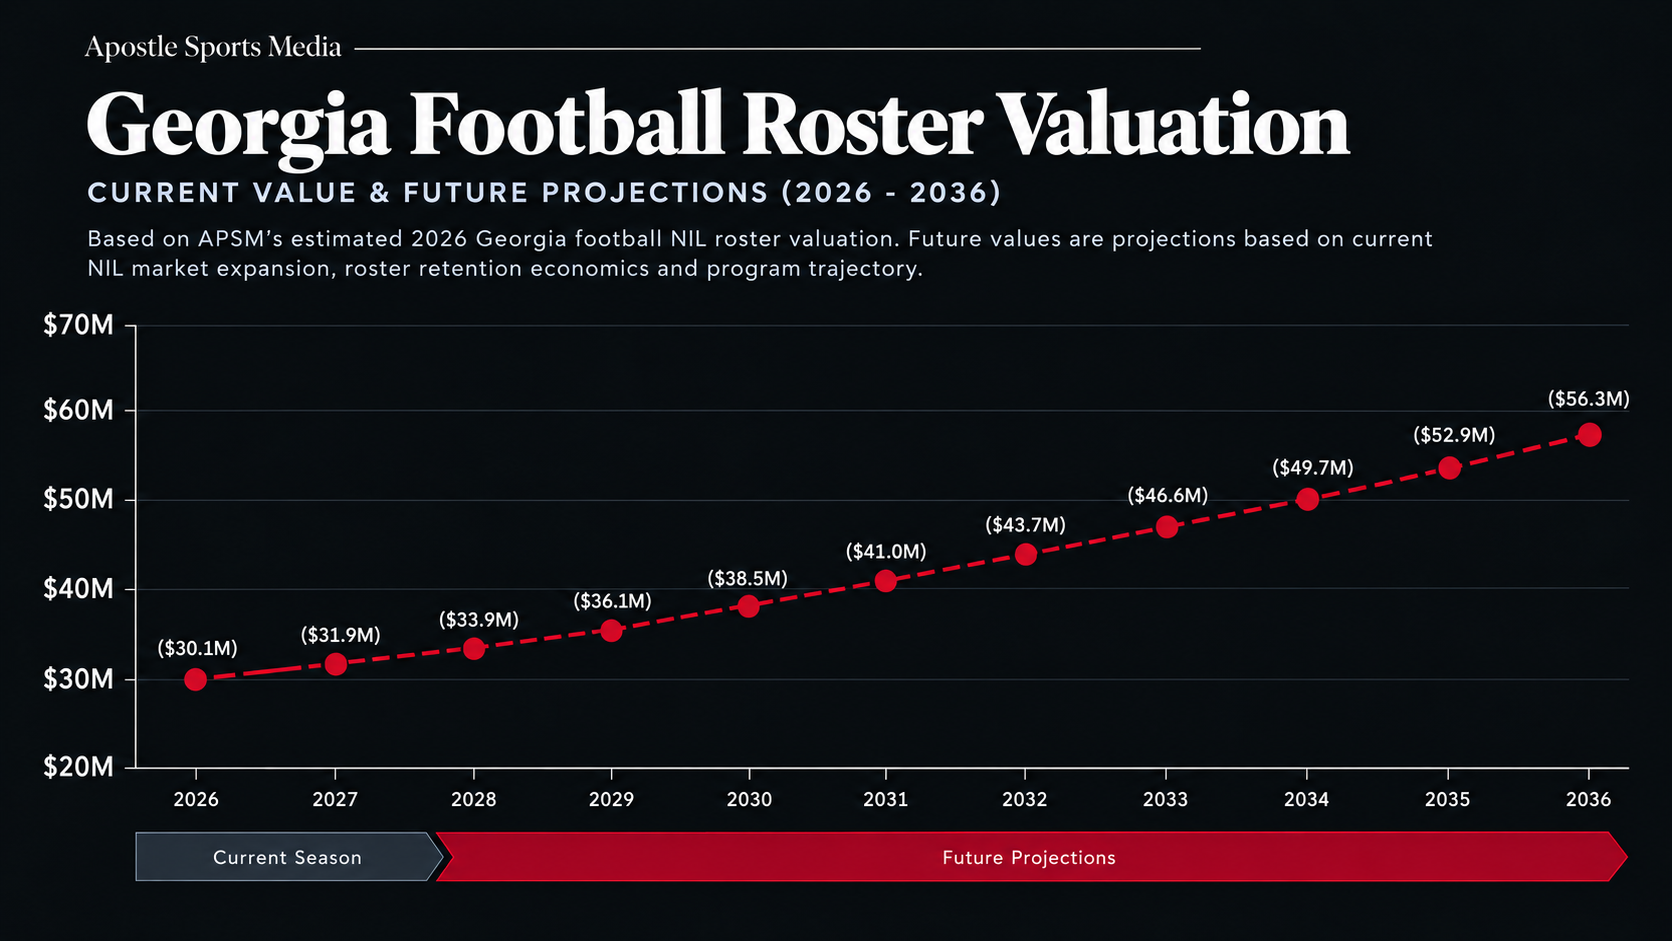
The first APSM projection below begins with the current ~$30.1 million midpoint inside Georgia’s $29 million – $31 million 2026 roster range and applies the same illustrative 7% annual market-growth assumption used throughout the CFB roster series.
It is not a prediction of an exact future payroll.
It illustrates what continued player-market expansion, direct compensation growth and Georgia’s ability to retain premium talent could mean for the economic value of the roster over the next decade.
How Georgia Built Its 2026 CFB Roster Around Retention
Approximately $22.3 million, or 74% of Georgia’s total estimated roster value, is attached to retained players. Portal additions account for another approximately $3.5 million, or 12%, and recruits account for approximately $4.3 million, or 14%.
That distribution is significant because the transfer portal has made retention an annual financial decision. A program that develops an athlete does not simply benefit from the player’s performance.
It also creates an asset that another school may attempt to acquire.
Georgia’s current roster suggests that the Bulldogs are relying primarily on protecting and developing their existing player base rather than rebuilding the majority of the roster through portal spending.
The numbers can be summarized as follows:
- Retained players: ~$22.3 million | 74%
- Portal additions: ~$3.5 million | 12%
- 2026 recruits: ~$4.3 million | 14%
Approximately three-quarters of Georgia’s estimated player value therefore remains tied to athletes already within the program. That provides a useful financial distinction between acquisition and retention. In the present college market, both can require significant capital.
Georgia’s Top Five 2026 Player Valuations
The top of Georgia’s roster is less concentrated than a traditional NFL-style payroll might suggest. The five highest-valued players collectively account for approximately $5.9 million, (~19.6% of the $30.1 million midpoint).
| Player | Pos. | Est. 2026 NIL Value | Share of Midpoint |
|---|---|---|---|
| Gunner Stockton | QB | $2,000,000 | 6.6% |
| Earnest Greene III | OT | $1,000,000 | 3.3% |
| Elijah Griffin | DT | $1,000,000 | 3.3% |
| Gabe Harris Jr. | EDGE | $1,000,000 | 3.3% |
| Juan Gaston | OT | $900,000 | 3.0% |
The current roster also includes seven-figure or near-seven-figure valuations for Drew Bobo, Ekene Ogboko, Jordan Hall, Isiah Canion and KJ Bolden, among others. That distribution indicates that Georgia’s value is not dependent on one offensive superstar.
Significant financial value exists along the offensive line and throughout the defensive front, which is consistent with a roster strategy built around depth at premium football positions.
Gunner Stockton | ~$2.0 Million | Quarterback
Gunner Stockton is Georgia’s highest-valued player at an estimated $2 million. The fifth-year quarterback returns after starting all 14 games in 2025, when he completed 269 of 386 passes for 2,894 yards and 24 touchdowns while adding 462 rushing yards and 10 rushing touchdowns.
He finished seventh in Heisman voting and was named SEC Championship Game MVP. Stockton’s valuation reflects the premium attached to an established quarterback, but his financial profile also demonstrates how school-related valuation and outside commercial income can coexist.
Stockton and Georgia tight end Lawson Luckie entered an NIL partnership with Associated Credit Union in 2025. ACU selected the two players as representatives because of their connection to Georgia communities and their ability to reach younger consumers.
Stockton also maintains an official NIL merchandise presence through Georgia’s licensed marketplace, providing another example of how an athlete can monetize his name and image independently of a single valuation figure.
The financial distinction remains important: the $2 million figure is an estimated market valuation, while the ACU partnership and merchandise revenue represent actual commercial opportunities that may exist separately.
Earnest Greene III | ~$1.0 Million | Offensive Tackle
Earnest Greene III is valued at approximately $1 million, making him one of Georgia’s highest-valued offensive linemen.
Greene enters 2026 as a fifth-year player and preseason All-SEC first-team selection. Georgia’s official roster notes that he anchored an offensive line that produced more than 32 points per game in 2025 and helped the Bulldogs rank among the SEC’s better teams in protection metrics.
His valuation demonstrates why offensive-line compensation has become an important component of roster economics. Protecting the quarterback is not simply a football consideration when that quarterback represents a multimillion-dollar asset.
The same logic applies to the rest of Georgia’s offensive line, where Drew Bobo, Ekene Ogboko and Juan Gaston all carry substantial market valuations.
Elijah Griffin | ~$1.0 Million | Defensive Tackle
Elijah Griffin is also valued at approximately $1 million, placing him alongside Greene among Georgia’s seven-figure players.
Griffin’s valuation reflects the market’s willingness to assign significant economic value to defensive-line talent. At premium positions, market value is increasingly connected not only to public visibility but to the scarcity of players capable of performing at an elite level.
Griffin’s public NIL profile also carries a commercial component. Georgia’s official NIL marketplace offers licensed merchandise using his name and likeness, demonstrating how even defensive players can participate in direct consumer monetization.
Gabe Harris Jr. | ~$1.0 Million | Edge Rusher
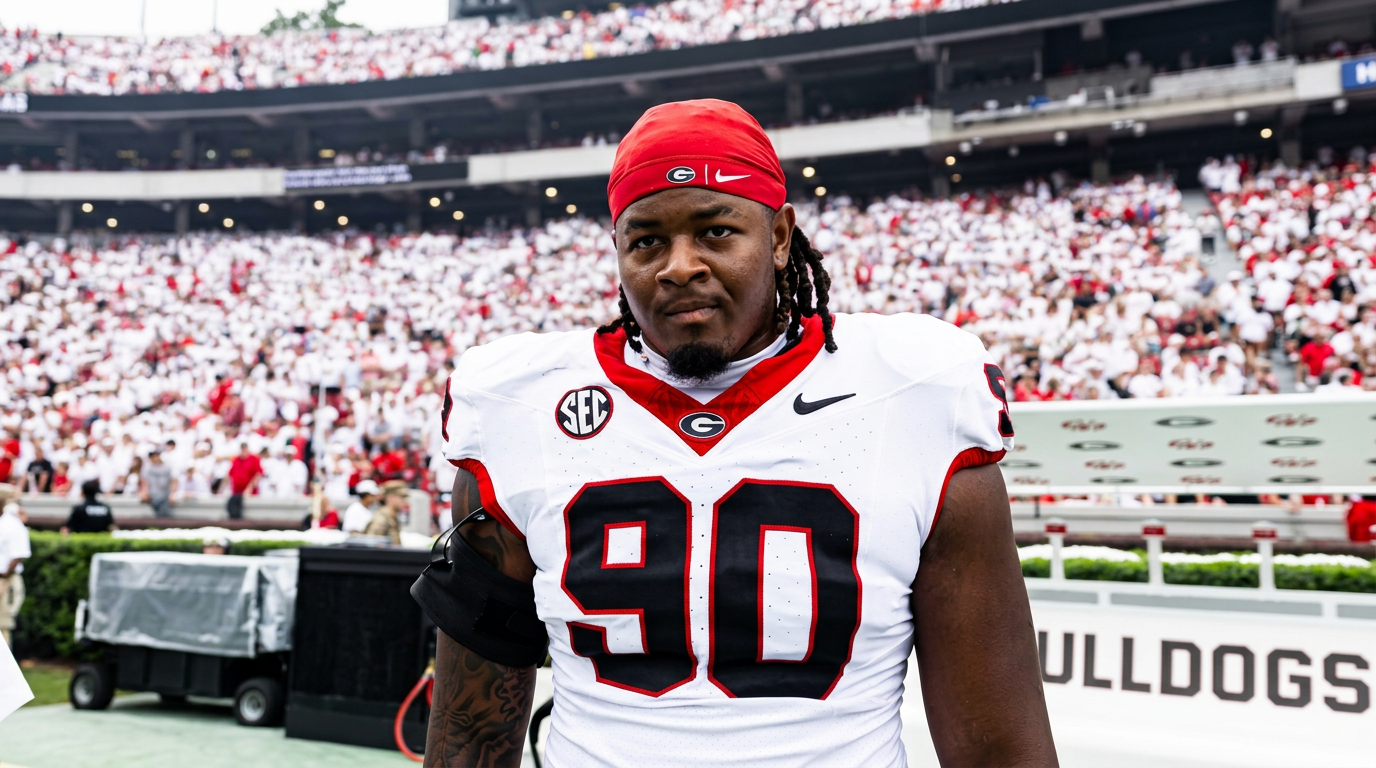
Gabe Harris Jr. carries an estimated valuation of ~$1 million, making him Georgia’s highest-valued edge defender in the current model.
Harris enters his senior season after starting 13 games in 2025, when he recorded 26 tackles and 6.5 tackles for loss. Georgia selected him to its 2026 preseason All-SEC third team.
The valuation places nearly $1 million of estimated market value on a player whose contribution is primarily defensive.
That is another indication that Georgia’s roster economics are built around football performance and positional scarcity rather than simply the athletes most recognizable to the general public.
Juan Gaston | ~$900,000 | Offensive Tackle
Juan Gaston is valued at approximately $900,000, giving Georgia another substantial investment along the offensive line. Gaston is a sophomore from Atlanta who played 13 games and made four starts in 2025.
At 6-foot-7 and 360 pounds, he represents the type of young, physically scarce offensive-line asset that programs attempt to retain and develop over several seasons.
His valuation reinforces the broader composition of Georgia’s roster: financial value is being distributed throughout the line of scrimmage rather than concentrated entirely in the quarterback position.
Georgia’s Roster Valuation Is Separate From Revenue Sharing
Georgia entered the House-settlement era by committing to fully fund the available first-year athlete-benefits pool.
The structure has since moved forward. For the 2026-27 academic year, participating institutions can provide up to approximately $21.58 million in schoolwide settlement-related benefits and direct payments to athletes.
That figure should not be interpreted as Georgia football’s payroll, nor should it simply be added to APSM’s $29 million – $31 million football roster-value range. They measure different things.
- $29 million–$31 million is APSM’s current estimate of Georgia football’s open-market player-value range.
- ~$30.1 million is APSM’s current working midpoint.
- ~$21.58 million is the current schoolwide benefits cap across all sports.
Legitimate, third-party NIL exists separately from both.
The distinction matters because institutional athlete compensation, football roster market value, independent NIL and the cost of operating Georgia athletics all interact without becoming one interchangeable pool of money.
| Financial Measure | Georgia 2026 Figure |
|---|---|
| Estimated football roster market value midpoint | ~$30.1M |
| University revenue-sharing commitment | $21.58M |
| Estimated retained-player value | ~$22.3M |
| Estimated portal-player value | ~$3.5M |
| Estimated recruit value | ~$4.3M |
The ~$30.1 million is an estimated market value midpoint of Georgia’s football players. The $21.58 million is the university’s annual direct-compensation commitment across its athletic program.
Actual player earnings depend on individual arrangements and can include compensation outside both headline figures. That distinction is important for agents and athletes because compensation can come from different entities with different contractual obligations, tax treatment and payment schedules.
Third-Party NIL Creates an Additional Commercial Market
Institutional compensation does not eliminate independent NIL opportunities. Georgia athletes can continue participating in legitimate third-party commercial agreements, and the broader NIL market has expanded considerably under the current system.
The College Sports Commission reported that more than $227 million in NIL deals were cleared during July and August 2026 alone, including approximately $188.6 million involving associated entities.
Georgia’s roster provides several examples of how that commercial market operates. In July 2026, six Georgia football players announced Nike NIL agreements: Kaiden Prothro, Elyiss Williams, Chris Cole, Ellis Robinson IV, KJ Bolden and Talyn Taylor.
KJ Bolden, for example, carries a current aggregate gross roster valuation of approximately $850,000 and is also a Nike athlete with licensed NIL merchandise available through Georgia’s marketplace.
These relationships demonstrate why an athlete’s total economic opportunity cannot be determined from one roster valuation.
The financial structure can include:
- Direct institutional compensation
- Associated-entity NIL arrangements
- Independent brand sponsorships
- Merchandising and licensing
- Appearances and promotional activity
- Social-media and content revenue
The exact combination differs by athlete, but the underlying principle applies across college sports.
Georgia’s Commercial Environment Is Part of the Financial Equation
Georgia’s athletic department is also expanding its own commercial ecosystem. In August 2026, Georgia announced a sponsorship with Progressive Insurance that includes branding at Sanford Stadium.
Georgia said the relationship, administered with Georgia Bulldogs Sports Marketing, provides additional resources for student-athletes while expanding the athletic department’s commercial revenue base. The significance extends beyond one sponsorship. An athletic department with a large national audience creates commercial inventory for corporations.
That institutional value can support the financial environment in which individual athletes operate, while successful athletes can simultaneously increase the visibility and marketability of the university brand.
The athlete, team and university therefore participate in an increasingly connected commercial ecosystem.
Kirby Smart’s $13 Million Contract Is Separate From Player Value
Georgia head coach Kirby Smart operates under a separate financial structure from the players. Smart’s compensation is not included in the $29 – $31 million roster valuation.
The University of Georgia approved a contract extension in 2024 that increased Smart’s annual salary to $13 million and extended his term through December 31, 2033. The agreement also increased his maximum annual bonus (incentives) opportunity to $1.55 million under the expanded College Football Playoff structure.
His contract represents compensation for the head coach, while the roster valuation represents an estimate of player market value. The comparison nevertheless illustrates the scale of Georgia’s football operation.
A program with approximately $29 – $31 million in estimated player market value is simultaneously committing $13 million in annual salary to its head coach, before considering signing bonuses and incentives, assistant coaches, recruiting operations, facilities, support staff and the other operational expenses associated with running a major SEC program.
The financial structure increasingly resembles a professional organization in which the value of the underlying talent and the compensation of the person managing that talent are distinct but interconnected.
Using the same standardized framework APSM applies when illustrating coaching compensation, Smart’s $13 million annual salary also provides a useful gross-to-net example.
If the full $13 million were modeled as W-2 compensation for a single filer, APSM estimates approximately $7.28 million could remain after 2026 federal income tax, employee Social Security and Medicare taxes and Georgia state income tax, before bonuses, itemized deductions, retirement contributions, benefits or individualized planning.
That represents roughly 56% of gross compensation under the standardized illustration. A $13 million coaching contract and a $13 million bank balance are two very different numbers.
APSM estimate only: Smart’s actual filing status, deductions, benefits, contract structure and tax return are private. The example illustrates the mechanics of high-income coaching compensation rather than estimating his private tax liability.
Gross NIL Value Is Not Net Income
The difference between gross valuation and actual financial wealth becomes particularly important for athletes.
Four concepts should remain separate:
- Market valuation: an estimate of what the athlete is worth in the market.
- Gross income: compensation received under contracts and arrangements.
- Net income: what remains after applicable taxes and expenses.
- Wealth: accumulated assets after spending, taxes and liabilities.
The IRS states that NIL income is generally taxable and can include cash, property or services. The specific tax treatment depends on how the athlete is compensated and structured, meaning not every NIL agreement should automatically be treated as identical 1099 income.
Athletes may have federal income-tax obligations as well as Social Security and Medicare or self-employment tax obligations depending on the arrangement.
Athletes should also maintain records of business expenses and monitor the states in which NIL services are performed because state tax obligations can arise outside the athlete’s primary residence. For a high-income athlete, the gross number is therefore only the beginning of the financial analysis.
Georgia’s 2026 Tax Environment
Georgia gives athletes a materially different tax environment from the no-income-tax states that appear elsewhere in the CFB roster series.
For tax year 2026, Georgia imposes a 4.99% flat individual income-tax rate and provides a $15,000 standard deduction for a single filer.
That does not mean a Georgia athlete simply loses 4.99% and keeps the rest.
Federal income tax remains the largest component for a seven-figure earner, while employment or self-employment taxes (form 1099), representation and multistate income can create additional drag.
Using the APSM Net Income Calculator, a standardized $2 million gross NIL example with Georgia as the primary jurisdiction, a 3% representation estimate and 0% personalized expenses produces approximately $1.079 million in modeled retained capital, or about 53.9% of gross.
Georgia’s 4.99% rate should therefore be viewed as one component of the athlete’s overall tax environment rather than the complete tax calculation.
For an athlete retaining Georgia as a long-term home base, however, the state rate can become financially meaningful once annual taxable income reaches hundreds of thousands or millions of dollars.

Georgia Bulldogs Roster Net Reality
Because individual agreements, tax returns and representation contracts are private, APSM cannot determine the exact take-home income of Georgia players from market valuations alone. The standardized player model uses the same core framework across schools:
- 2026 progressive federal income-tax brackets
- self-employment/FICA treatment for the standardized NIL illustration
- the athlete’s primary-state income-tax structure
- a 3% contract-negotiation / representation estimate
- 0% invented personalized expenses
That final assumption is intentional.
Training, housing, travel, family support, legal costs and the operating expenses of an athlete’s NIL business can vary enormously from player to player. At the standardized $2 million Georgia benchmark, the model retains approximately 53.9% of gross value, or roughly $1.08 million.
| Player | Gross Valuation | Illustrative Deductions | Illustrative Net Capital |
|---|---|---|---|
| Gunner Stockton | $2,000,000 | ~$921,155 | ~$1,078,845 |
| Earnest Greene III | $1,000,000 | ~$443,530 | ~$556,470 |
| Elijah Griffin | $1,000,000 | ~$443,530 | ~$556,470 |
| Gabe Harris Jr. | $1,000,000 | ~$443,530 | ~$556,470 |
| Juan Gaston | $900,000 | ~$395,767 | ~$504,233 |
Converting NIL Income Into Long-Term Wealth
The greatest financial advantage available to a high-earning college athlete is not simply earning seven figures. It is having access to meaningful capital at an unusually young age.
Using the standardized model above, a $2 million Georgia NIL example leaves approximately $1.08 million of illustrative retained capital.
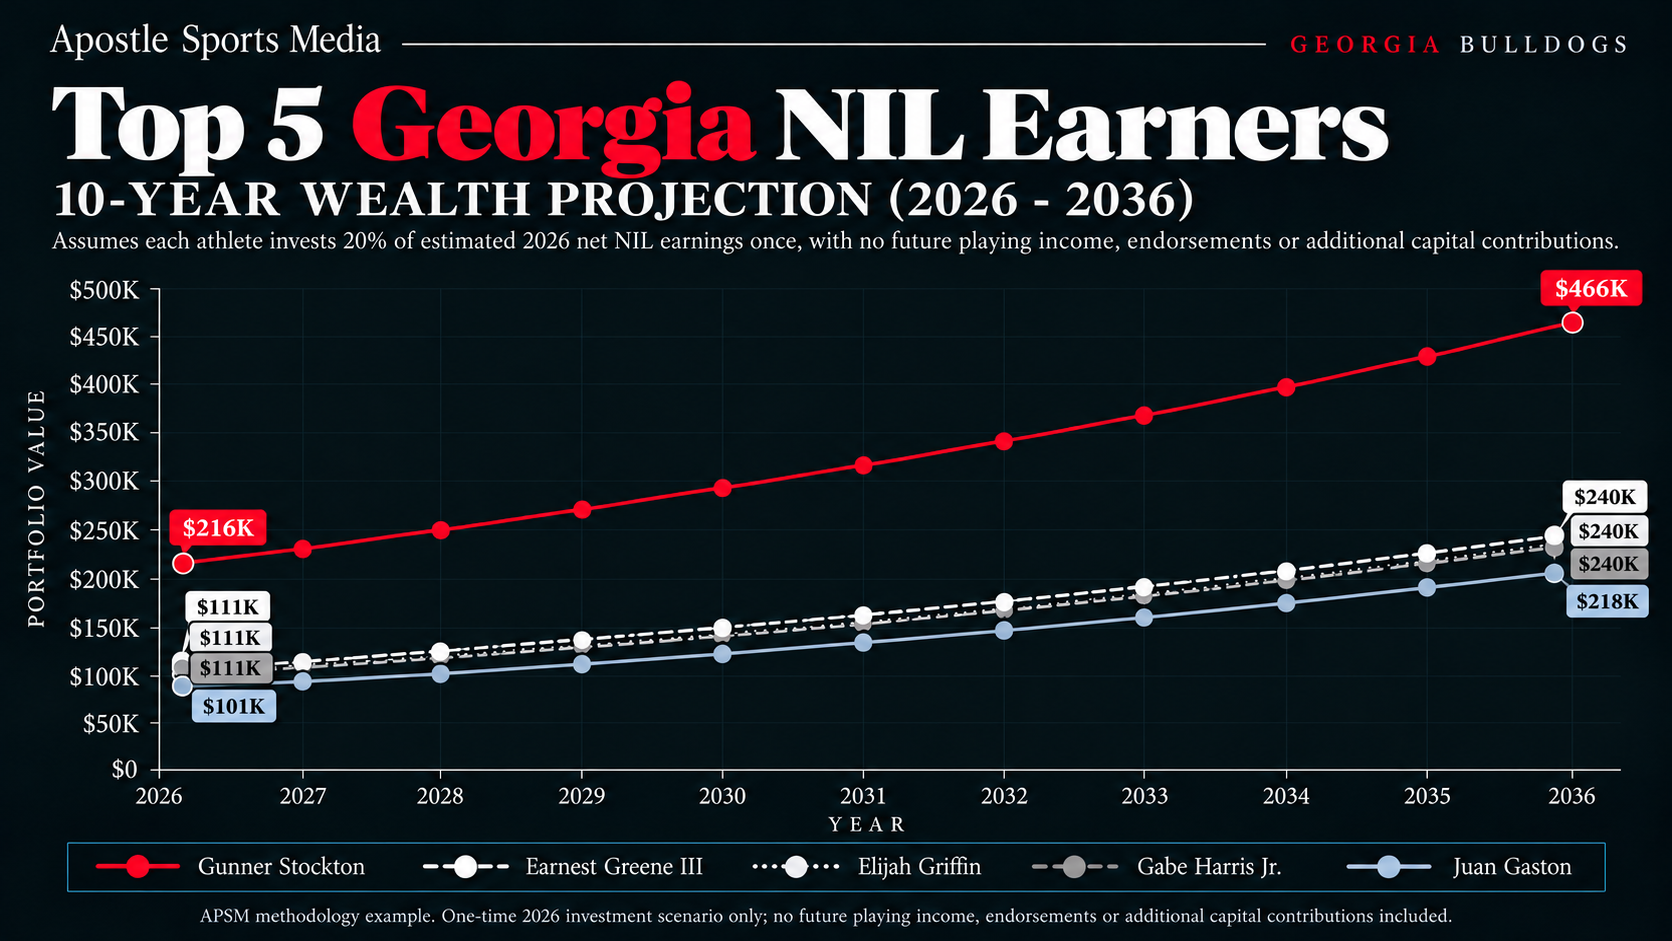
An athlete still needs liquidity for housing, transportation, family obligations, training, taxes and ordinary life. In the standardized APSM scenario, investing 20% of modeled retained income into historically proven investment vehicles (index funds | mutual funds) would put approximately $216,000 to work immediately.
That capital does not have to remain in one asset class. Diversified investments, real estate, business ownership and liquid reserves can all serve different purposes within a broader financial plan.
Diversified Investments
For APSM’s standardized wealth scenario, 20% of modeled net income is invested into a diversified long-term portfolio.
The objective is not to predict a specific market return or tell an athlete what to purchase; it is to demonstrate how early capital can continue producing value after the NIL payment itself is gone.
A player earning meaningful money at 20 years old has decades of potential compounding ahead of him, which can materially change the financial starting point of a later professional career.
Real Estate
If the athlete chose to allocate a separate portion of retained capital toward real estate, that money could represent part of the equity required for a larger purchase. Athletes do not necessarily need to buy a luxury residence simply because they have the ability to make the down payment.
A more disciplined approach could involve a primary residence, multifamily property or professionally managed investment property selected according to the property’s underlying economics.
Athens itself remains relatively affordable compared with many large U.S. markets. Zillow’s July 2026 data put the average Athens home value at approximately $344,516, with a median sale price near $344,000.
Average rent was approximately $1,629.
That does not mean Athens real estate should automatically be considered an investment opportunity. It demonstrates that a top-paid athlete has a much larger range of potential property strategies than purchasing a multimillion-dollar personal residence with a Jumbo Loan.
An athlete could potentially use their college earning window to build brand equity, establish a business structure where appropriate and accumulate substantial housing equity while preserving liquidity elsewhere.
What One Season of Georgia NIL Income Could Become
A college athlete does not need three identical seven-figure seasons for NIL income to materially change his financial future. To isolate the value of the capital already available today, APSM’s standardized wealth model makes a deliberately conservative assumption: after the 2026 season, the athlete never earns another dollar from football.
No future Georgia NIL payments.
No endorsement growth.
No NFL rookie contract.
No additional investment contributions.
The purpose is to show that an athlete does not need an NFL contract or multiple seven-figure college seasons for one high-income window to create meaningful long-term financial momentum.
Instead, the model estimates each of Georgia’s five highest-valued players’ modeled net capital, invests 20% once, and allows only that original investment to compound through 2036.
That removes the need to predict future contracts and shows what a single season of high-level college earning power can accomplish by itself.
Why This Data Matters
The projection is not intended to predict the exact future net worth of any Georgia athlete. Investment returns fluctuate, personal spending differs, and every player will eventually make different decisions with his money.
The value of the exercise is the starting point.
An athlete who turns one college season into six figures of invested capital enters the rest of his career in a fundamentally different financial position from a player beginning with no productive assets.
If that athlete later reaches the NFL, the professional contract does not have to become the beginning of wealth creation. It can become the next contribution to a portfolio that already exists.
That is one of the most consequential changes created by modern college-athlete compensation: elite players can begin building long-term assets before ever having a professional career, if they do at all.
APSM Net Retention Score: Georgia 59/100
Georgia’s broader financial position becomes easier to compare once the player-specific Net Reality calculations are separated from APSM’s standardized Net Retention Score.
Under the benchmark, every jurisdiction begins with the same $1 million of gross athlete income.
Agent fees and personalized career expenses are removed so the score isolates the underlying tax environment rather than an athlete’s individual representation structure or spending decisions.
For Georgia, that produces an APSM Net Retention Score of 59/100.
That score should not be confused with the approximately 53.9% retention modeled at the standardized $2 million Georgia player example.
The player model starts with a different gross-income level and includes a 3% representation assumption. The Net Retention Score fixes gross income at $1 million and removes representation and personalized expenses so Georgia can be compared directly with Texas, Alabama, Mississippi and every other jurisdiction under the same tax-only framework.
Georgia’s 4.99% state income tax creates more drag than a no-income-tax state such as Texas, but the state remains materially below several of the highest-tax athlete markets.
The score does not mean every Georgia athlete literally keeps 59 cents of every dollar. It is the standardized state-level benchmark underneath the broader Net Reality calculation.
APSM Net Retention Score: Georgia — 59/100
Financial Implications of Georgia CFB Roster’s Net Reality for Athletes, Agents and Sponsors
For Athletes
Georgia demonstrates why gross compensation alone is an incomplete measurement of financial opportunity.
The state’s 59/100 APSM Net Retention Score gives athletes a middle-to-upper tax position relative to several major athlete markets, but gross income still has to survive federal taxation, Georgia income tax, income structure, representation and personal expenses before it becomes lasting capital.
A ~$2 million valuation can create extraordinary earning power.
It does not automatically create a ~$2 million balance sheet.
For Agents
Georgia’s roster is overwhelmingly retention-driven.
Approximately 74% of the current ~$30.1 million midpoint is attached to athletes already developed inside the program, making retention negotiations, portal leverage, outside commercial opportunities and the eventual net value of each agreement increasingly relevant parts of representation.
The financial question is no longer simply what another school will offer. It is what each competing offer becomes after structure, taxes, fees and location are considered.
For Sponsors
Georgia’s athlete economy extends well beyond institutional payments. Nike agreements, licensed merchandise, local partnerships and Georgia’s broader commercial audience create independent opportunities for athletes to monetize their names and visibility outside the university’s direct-compensation structure.
Performance builds attention. Georgia’s brand amplifies it. Third-party partners determine how some of that attention becomes commercial income.
For Georgia
Georgia’s financial challenge is capital allocation.
The athletic department must operate inside the current schoolwide benefits cap, retain elite players, selectively use the portal, recruit high-school talent, compensate a $13 million head coach and operate one of the largest football enterprises in college sports.
Those expenses interact.
They do not belong in one fictional payroll number.
Bottom Line
Georgia currently sits inside APSM’s estimated $29 million – $31 million 2026 football roster-value range, with the current player-level dataset centered around a ~$30.1 million working midpoint.
Approximately 74% of that value is attached to retained players, while portal additions account for roughly 12% and incoming recruits represent another 14%.
That distribution is the financial identity of Georgia football.
The Bulldogs are not primarily paying to reconstruct the roster every offseason. They are protecting a large portfolio of talent already developed inside the program while selectively adding new capital through the portal and recruiting market.
Around those athletes sits a much larger sports enterprise: the $21.58 million 2026-27 schoolwide benefits cap, independent NIL and sponsorship activity, a $13 million head coach and the infrastructure required to operate one of college football’s largest programs.
Those figures do not belong to one financial bucket.
For the athlete, Georgia’s 59/100 APSM Net Retention Score then provides the tax-only starting point underneath the player-specific calculation.
A ~$2 million market valuation is not ~$2 million of wealth.
- Gross value has to become actual income.
- Income has to survive taxes and fees.
- Retained capital then has to survive spending.
Whatever remains must become savings, investments, business equity, real estate or another productive asset before temporary earning power becomes lasting financial security.
That is the Net Reality.
Georgia 2026 CFB Roster FAQs
What is Georgia football’s 2026 roster worth?
APSM currently places Georgia’s 2026 football roster inside an estimated $29 million – $31 million open-market range, with a current working midpoint of approximately $30.1 million. The range reflects the reality that player market value can move with production, injuries, role changes, transfer leverage and commercial demand.
Who are Georgia’s five highest-valued football players in 2026?
Georgia’s five highest-valued players carry approximately $5.9 million in combined estimated market value, equal to roughly 19.6% of APSM’s current ~$30.1 million working midpoint.
- Gunner Stockton (QB): ~$2.0M
- Earnest Greene III (OT): ~$1.0M
- Elijah Griffin (DT): ~$1.0M
- Gabe Harris Jr. (EDGE): ~$1.0M
- Juan Gaston (OT): ~$900K
The distribution is unusually balanced for an elite roster, with major value concentrated not only at quarterback but along Georgia’s offensive and defensive fronts.
Is Georgia actually paying its football players $29 million–$31 million?
No. The $29 million–$31 million range represents APSM’s estimate of Georgia football’s open-market player value, not a disclosed university payroll. Direct institutional revenue sharing, independent third-party NIL, sponsorship income and the broader cost of operating Georgia football are separate financial categories.
How much does a $2 million Georgia NIL athlete keep under the APSM model?
Using APSM’s standardized 2026 framework with progressive federal taxation, self-employment/FICA treatment, Georgia’s 4.99% state-income-tax structure, a 3% representation estimate and 0% personalized expenses, the $2 million benchmark models approximately $1.08 million of retained capital, or about 53.9% of gross. Actual results can vary materially based on income structure, filing status, deductions, residency and individual circumstances.
What is Georgia’s income tax rate for athletes in 2026?
Georgia imposes a 4.99% flat individual income-tax rate for 2026. High-income Georgia athletes can still owe federal income tax, applicable employment or self-employment taxes and potentially taxes in other jurisdictions when income is earned elsewhere.
Under APSM’s standardized $1 million tax-only benchmark, Georgia produces a Net Retention Score of 59/100.
Next Reads
- Alabama 2026 CFB Roster Valuation: Net Reality
- Ole Miss 2026 CFB Roster Valuation: Net Reality
- Ohio State 2026 CFB Roster Valuation: Net Reality
- Inside the House v. NCAA Settlement and Its Impact on College Sports
- Georgia Athlete Taxes
Disclaimer: This article contains general financial information for educational purposes and does not constitute professional advice. APSM estimates are derived from publicly available information, tax assumptions, finance modeling, and industry-standard fee structures. Actual earnings may vary based on residency elections, private contract provisions, image/media rights agreements, bonuses, and tax filings.